A Market of Two Minds — Seventh Edition, Fall 2026
The Summit is Alta West Mortgage Capital Corporation’s (Alta West Capital) quarterly journal for investors and mortgage professionals, as well as future stakeholders. It is a reflection of the philosophy that has shaped our business for over thirty years. We believe every successful investment, every successful deal, begins with a well-structured loan shaped to serve a borrower responsibly while safeguarding investor capital. Through market commentary, economic analysis, portfolio insights and perspectives from our leadership team and other financial professionals, The Summit examines the principles of disciplined lending, prudent risk management and thoughtful capital allocation that continue to define AWC across every market cycle.
This issue of the Summit explores how an uncertain market impacts investors, mortgage professionals, and borrowers alike, and how Alta West aims to be their companion through it all.
One Market, Three Perspectives
For Investors
2026 marks 35 years of Alta West Capital serving investors and the Canadian real estate professional alike. This year, we’ve noticed that confusion and concern are chief among the sentiments of financial professionals when discussing the market at large. On October 28, the Bank of Canada raised its policy rate to 2.50% while at the same time, bond yields rose and inflation paints an equally divided picture: energy prices pushed headline CPI to 3.03%, while underlying measures remained near 2%, leaving sharply conflicting views of the outlook.
In light of this, we want to reflect on the history of this company. Alta West was founded during the early-1990s recession, so a difficult market was the one AWC was born into. From the outset, Alta West has strived to build and manage its fund portfolios with a focus on capital preservation and consistent income. We are proud of the funds’ historical performance in pursuit of these objectives; First Place, Diversified and Premiere have never experienced a negative annual return. Their storied history has seen the dot-com bubble burst, the 2008-09 global financial crisis come tumbling down, the 2014-15 oil crash swerve Alberta’s economy into the ditch, COVID’s global disruption in 2020 and the ensuing inflation shock through 2022. Even the energy shock that happened this year. Alta West has navigated market volatility and tumult without needing to resort to major deviations in our lending practices.
That is precisely our management philosophy. We do not take on undue risk; we stay within our mandated parameters, and underwriting standards. Nothing enters our portfolio without passing every one of those standards, file by file, through our Lending Committee.
Our Chief Risk Officer, Brent Shaw, speaks to this:

“There is always going to be uncertainty in the market, and we can’t control where interest rates or property values will go. What we can control is the quality of our underwriting decisions. We focus on understanding the borrower, the security, and the risks associated with each mortgage before deciding whether it is a loan we are comfortable funding.”
Brent Shaw · Chief Risk Officer
As a testament to the discipline that has long been the cornerstone of the fund’s success, Diversified Mortgage Investment Corporation has just received its 6th straight positive rating from FRC.
This September, Fundamental Research Corp. (FRC) published its 2026 report on Diversified, reiterating an overall rating of 2 (Very Good Return to Risk Ratio) and a risk rating of 2 (Below Average Risk), the highest rating and lowest risk band FRC currently assigns across its coverage. The report highlights the fund’s record portfolio growth this past fiscal year, its improving risk profile, and the monthly, no-fee redemption feature that distinguishes Diversified from many of its peers. The full report, including FRC’s methodology and disclosures, is available on our website.
FRC receives fees from the fund for its research coverage; please see the disclosure section therein.
For Brokers
For mortgage brokers, market uncertainty shows up materially in the form of files on your desk. Traditional lenders continue to increase and narrow their specific lending criteria. Borrowers who may have been straightforward approvals in a different environment may now find themselves outside conventional lending parameters for reasons that have little to do with their ability to repay.
That is where the alternative market has a role to play.
Armando Diseri, Chief Sales Officer, shares his thoughts:
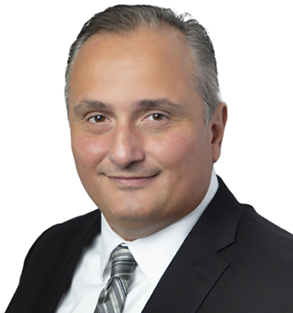
“These are challenging times, and people need a bridge. That is where the private space and the MIC come in. More and more, we’re seeing situations where we can help someone consolidate their debt, or put the financing together for a home, when the banks no longer have room for them. That’s where we’re excelling right now; helping Canadians, and we’re proud of it.”
Armando Diseri · Chief Sales Officer
Broker of Record, Jared Morrison speaks to this too:
“Be patient, my friends. I find that the brokers and realtors tend to really focus on whether average prices are increasing or decreasing because they feel that determines if it is a good time to be in business or not. But the reality is that…
there is always a transaction that needs to be financed.
Control what you can, but…learn how to work in an up or down market because it is all the same at the end of the day. Someone is selling, someone is buying, someone is renewing, refinancing, consolidating debt, etc. Focus on your business and figure out what you can do to attract new business.”
Jared Morrison · Broker of Record
For Borrowers
For borrowers, an uncertain market can be particularly frustrating.
Rates may be moving in one direction while affordability suggests another. A bank’s criteria can change even when your circumstances haven’t, and what was once straightforward has been complicated by factors outside your control.
A bank saying no does not necessarily mean the transaction does not work. It may simply mean it does not fit that lender’s model. Alternative lending exists to bridge that gap.
The fundamentals remain the same: the borrower needs a viable path forward; the property must provide appropriate security, and the mortgage structure must make sense for both sides. That is why disciplined underwriting matters.
“At Alta West Capital, we measure success by more than investment performance. Our goal is to enable financial growth and opportunity for every stakeholder we serve. We want everyone who works with us to be able to put themselves in a better financial position than when the relationship began.”
George Botros · Chief Executive Officer
Behind Every Deal, a Team
Between every borrower, investor, broker and stakeholder stands a dedicated team member from Alta West — the people that make it all possible. Our team is grateful to serve you and unlock possibilities, together.
Your Management Team




A Final Word
A market of two minds can make one crave the comfort of certainty.
Which forecast is right? Where will rates go? Will housing recover? Will inflation persist?
There is value in asking those questions, but none can claim they have the answers. All we can do is operate based on the knowledge we have. At AWC, we know the borrower. We know their credit history. We know the collateral. We know the structure. We know the risks we are willing to accept and the risks we are not. And we can build a business capable of operating through more than one possible future. One rate decision does not define a cycle, just as one forecast does not determine a lending strategy. For 35 years, Alta West Capital has built its business around something more durable: disciplined decisions made one mortgage at a time.
The market may be uncertain. But our discipline is single-minded.
Alta West Capital is always looking to connect with excellent people. If you’re a mortgage professional, an investor or stakeholder who shares our values, please see below how you can get in touch with us and help us continue to strive for excellence.
Warm regards,
The Alta West Capital Team